I rate the BILT Palladium A tier. With enough eligible housing spend, its Flexible BILT Cash option can make everyday purchases behave like as much as 3.33 BILT Points per dollar in my framework. But that is combined math—not BILT’s advertised earn rate—and the $495 annual fee will not work for everyone.
It is my catch-all because 2X earning, housing rewards, and BILT’s transfer partners replace much of the usual category juggling.
BILT Palladium at a glance
These terms were checked against BILT’s official pages on August 26, 2026. Offers and benefits can change.
| Feature | Current terms |
|---|---|
| Welcome offer | $300 BILT Cash at account opening, plus 50,000 BILT Points and BILT Gold status after $4,000 in eligible everyday spend within 90 days |
| Annual fee | $495; $95 for each authorized user |
| Everyday purchases | 2X BILT Points on eligible purchases other than housing |
| Flexible BILT Cash | 4% BILT Cash on eligible everyday spend; redeem it to unlock up to 1X on eligible housing payments |
| Housing-only alternative | 0X–1.25X on eligible housing payments based on the ratio of everyday spend to housing spend; no 4% BILT Cash |
| Annual benefits | $200 BILT Cash and a $400 BILT Travel Hotel Credit, split into two $200 half-year credits |
| Lounge access | Priority Pass for the primary cardholder and up to two guests under the current benefit guide |
| APR | 10% introductory purchase APR for 12 billing cycles; then 26.74%–34.74% variable |
| Foreign transaction fee | $0 |
Housing payments do not count toward the $4,000 welcome-offer requirement, and current terms limit the offer to eligible new applicants under BILT’s Card 2.0 offer terms. Check the live BILT Palladium offer and terms before applying.
Why I call it a 3.33X catch-all
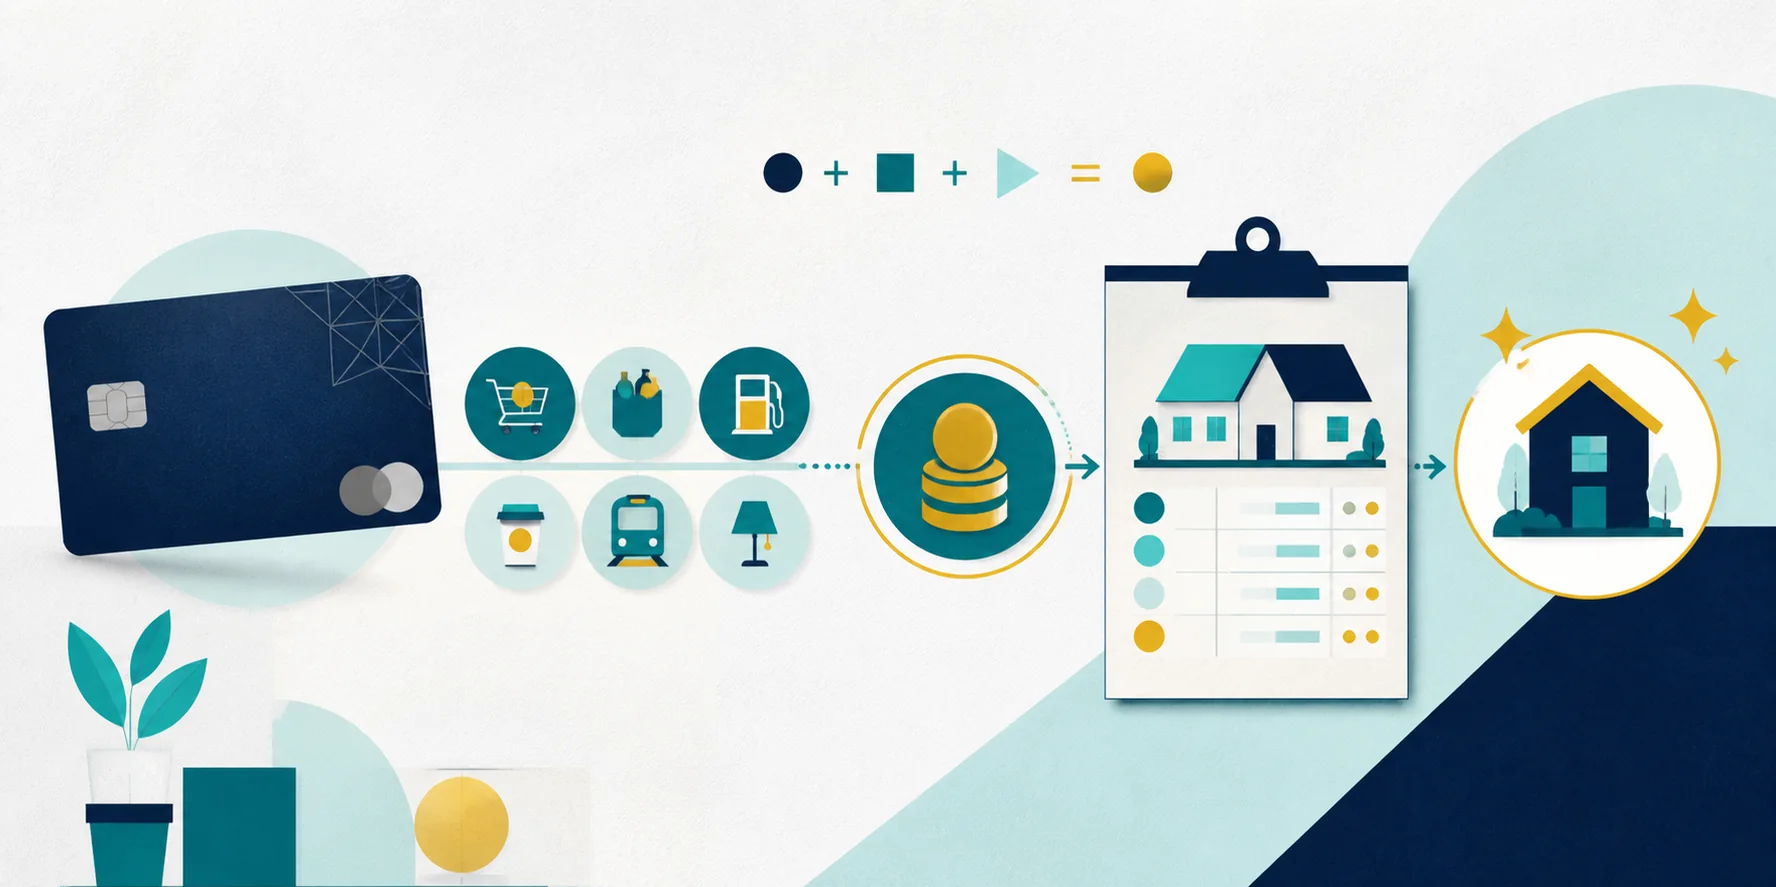
Under Flexible BILT Cash, $1 of eligible everyday spend earns two BILT Points and four cents of BILT Cash. BILT currently lets $3 unlock 100 points on an eligible housing payment, so four cents can unlock 1.33 points. I attribute those housing points to the spending that generated the cash:
2 base points + 1.33 housing points = 3.33 points per everyday dollar
This is not a literal 3.33X line on the statement. The 2X posts on the purchase; the other 1.33X requires BILT Cash and sufficient eligible housing spend. Full 3.33X requires housing spend to be at least one-third higher than everyday spend—or everyday spend to be no more than 75% of housing spend.
For example, $30,000 of eligible everyday spend earns 60,000 points and $1,200 BILT Cash. With at least $40,000 of eligible housing payments, that cash can unlock another 40,000 points. The combined 100,000 points equal 3.33 points per everyday dollar.
If housing spend is lower, the point-only rate falls. Remaining BILT Cash may still be useful elsewhere, but do not assign it a value you may never realize.
The earning is strong; the mechanics are not simple
BILT Palladium earns 2X on eligible everyday purchases. Current partner bonuses can lift eligible BILT Travel hotels to 4X, flights to 3X, Lyft to 4X, and Neighborhood Dining to as much as 5X.
Flexible BILT Cash supports my framework. The Housing-only alternative earns 0X–1.25X on eligible housing according to spending ratios but gives up the 4% BILT Cash. The selection applies for the billing cycle. BILT Cash also expires at year-end except for up to $100 that can roll over, so excess balances need a plan.
BILT also lets $200 BILT Cash add 1X on up to $5,000 of eligible purchases, up to five times a year. That Point Accelerator is separate from my housing calculation; counting the same BILT Cash in both places would double-count value.
The $495 annual-fee test
BILT presents $600 of annual credits, but I do not value them at face value. The hotel benefit arrives as two $200 credits for eligible portal bookings of at least two nights, with no rollover between half-year periods. In my price comparisons, portal rates have often absorbed part of the savings, so I assign the $400 credit no more than $200 of value.
The separate $200 BILT Cash benefit can unlock about 6,666 housing points at the current rate. At a deliberately conservative one cent per point, I value that at about $66.66. My conservative fee math is therefore:
$495 - $200 - $66.66 = $228.34, or roughly $230.
Priority Pass can narrow that gap if you lack lounge access; it adds little if another card already provides it. Count what each benefit replaces in your budget, not its printed value.
My two-cent minimum valuation for well-used BILT transfers depends on finding an award for a real trip. High cents per point do not rescue a poor itinerary. Use the point-transfer checklist before moving anything.
What has worked for me
I use BILT Palladium for general spending and eligible mortgage and HOA payments through BILT. After a housing payment posts, BILT debits my linked bank account; I redeem BILT Cash to unlock the points. The core flow has worked smoothly. BILT Palladium helped me reach BILT Platinum in June 2026 after I exceeded $50,000 of qualifying annual spend, but I have not used a Platinum transfer bonus—I am waiting for one tied to a real need.
When housing cannot absorb every dollar, I sometimes use BILT Cash at Walgreens or with Lyft and have used it for a couple of hotel bookings. That flexibility matters.
Consider an illustrative $10,000 tuition bill with a 2.9% fee. If the $10,290 charge is eligible and at least $13,720 of housing capacity exists, my framework produces 34,300 points. At a conservative one cent each, that is $343—only $53 above the fee. Merchant coding, housing capacity, award availability, transfer timing, and redemption value all have to cooperate. Never pay a fee merely because “3.33X” sounds large.
The exclusions and weak spots matter
Direct tax payments do not earn BILT Points or BILT Cash under current terms. Property taxes included inside an eligible BILT Housing Payment are a narrow exception; a direct charge through a tax processor is different. That exclusion is the main reason BILT Palladium is A tier rather than S tier for me.
BILT Palladium’s other weaknesses are more familiar:
- The $495 fee is real, the 3.33X outcome needs substantial housing capacity, and BILT Cash above the $100 rollover limit can expire.
- Hotel credits require two-night portal bookings and may not deliver face value.
- The Neighborhood ecosystem is far stronger in New York City than in many other markets.
- Program mechanics and transfer promotions can change.
BILT Palladium does include rental-car coverage, trip cancellation and interruption protection, trip-delay reimbursement, purchase assurance, cellular-phone protection, and other Mastercard benefits. Each has payment requirements, limits, and exclusions, so read the current Guide to Benefits before relying on it for a trip or purchase.
Who should consider BILT Palladium?
BILT Palladium makes the most sense for someone who:
- Has enough eligible rent, mortgage, or related housing spend to use the BILT Cash productively
- Wants a powerful catch-all earning structure and values transferable points
- Can use the hotel credits without changing plans or overpaying through the portal
- Pays in full and earns enough incremental value to cover the remaining fee with room to spare
It is weaker when housing spend is low, annual spending is modest, the local BILT ecosystem is thin, or a simpler card already covers the need. Start with a 20-minute points inventory, then build the strategy around the trip rather than the card.
Final verdict
BILT Palladium is not merely a housing-points card. With the right spending pattern, it is an unusually strong catch-all with a plausible 3.33X combined return. Otherwise, it is a complicated $495 card whose credits may look better on paper.
For me, the earning and transfer partners win. For everyone else, compare eligible everyday spend, housing spend, and benefits you would use anyway. If they do not cover roughly $230 of conservative net cost with room for complexity, BILT Palladium should not make the cut.
If you want help deciding whether BILT Palladium deserves a role in your setup, first compare transferable points with airline miles, then explore the Points Earning Strategy Call. The goal is to fit earning to your real spending and travel plans, not to collect premium cards.
This article provides general educational information, not individualized financial, tax, legal, or credit advice. Card terms and personal circumstances vary.